The entity structuring, depreciation, and retirement moves a licensed CPA and tax attorney design together, before the year closes, so the plan holds up if the IRS asks questions later.
Basic tax planning takes the deductions the tax code hands you automatically — a home office, a mileage log, a retirement contribution. Advanced tax strategy restructures how income is earned and held in the first place, so more of it never becomes taxable income to begin with.
That distinction is the whole reason two credentials exist under one roof here instead of a CPA who preps and a separate attorney you call when something goes wrong. Tax planning looks forward, and the advanced tier of that planning covers entity selection, real estate cost recovery, and retirement plan design, not just this year's return.
There's no single IRS definition of high net worth — the tax code doesn't use the term. The SEC's accredited-investor standard (a net worth over $1 million, excluding a primary residence) is the closest official benchmark, but for tax planning purposes the more useful marker is whether your income sources have gotten complex enough that a single deduction stops moving the number. Business owners, real estate investors, and executives with equity compensation typically cross that line well before they'd meet a formal net-worth threshold.
Think of it as three tiers: tax preparation files what already happened and suits anyone with a simple, stable return; tax planning adjusts decisions before year-end and fits business owners and real estate investors; advanced tax strategy restructures entities, depreciation, and retirement design together, built for high-income earners and business owners with multiple income sources. It's why the entity a business owner chooses, and how they're paid out of it, affects self-employment tax, retirement contribution limits, and audit exposure all at once.
Every engagement is tailored to your situation. Below are the specific areas we cover.
Entity type optimization, owner compensation design, and income allocation strategies that affect self-employment tax, retirement contribution limits, and audit exposure together.
Reclassifying components of a commercial or investment property — fixtures, flooring, site improvements — out of a 27.5- or 39-year depreciation schedule and into 5-, 7-, or 15-year categories, for qualifying assets like car washes, fuel outlets, mobile home parks, and storage facilities. Study cost depends on the property's size, type, and complexity — we price each one after reviewing the specific asset.
Renewable energy projects, opportunity zones, and oil and gas working interests.
Tight capture of existing spend, salary/dividend/bonus optimization, retirement plan design, and fringe benefits.
Discount asset gifting, donor advised funds, charitable remainder and lead trusts, and qualified charitable distributions.
Energy and clean technology credits, employment-related credits, and federal and state credit purchasing.
Multi-year gain spreading, charitable coordination, and opportunity zone integration ahead of a major sale, exercise, or payout.
Get a quick, federal-only estimate for your situation, then talk to an attorney who is also a licensed CPA about the strategies that apply to you.
Estimate only — not tax or legal advice. Federal figures for tax year 2026 only; does not account for state tax, AMT, the Net Investment Income Tax, credits, or Qualified Business Income wage limitations. Schedule a consultation for a strategy tailored to your situation.
Ready to see which of these strategies actually apply to you?
Schedule your consultationSpeak with an attorney who is also a licensed CPA. Your consultation is confidential.
From your first call to long-term strategy, here is exactly what to expect when you work with us.
Share your income picture, entities, major assets, and any upcoming liquidity events. No obligation — just clarity on what is possible.
We analyze your returns, map applicable strategies, and show you dollar-specific projections before you commit to anything.
We handle the documentation, entity work, elections, and coordination with your existing advisors as part of the engagement.
Tax law and your circumstances change. We revisit the plan as they do, so it stays accurate and compliant year over year.
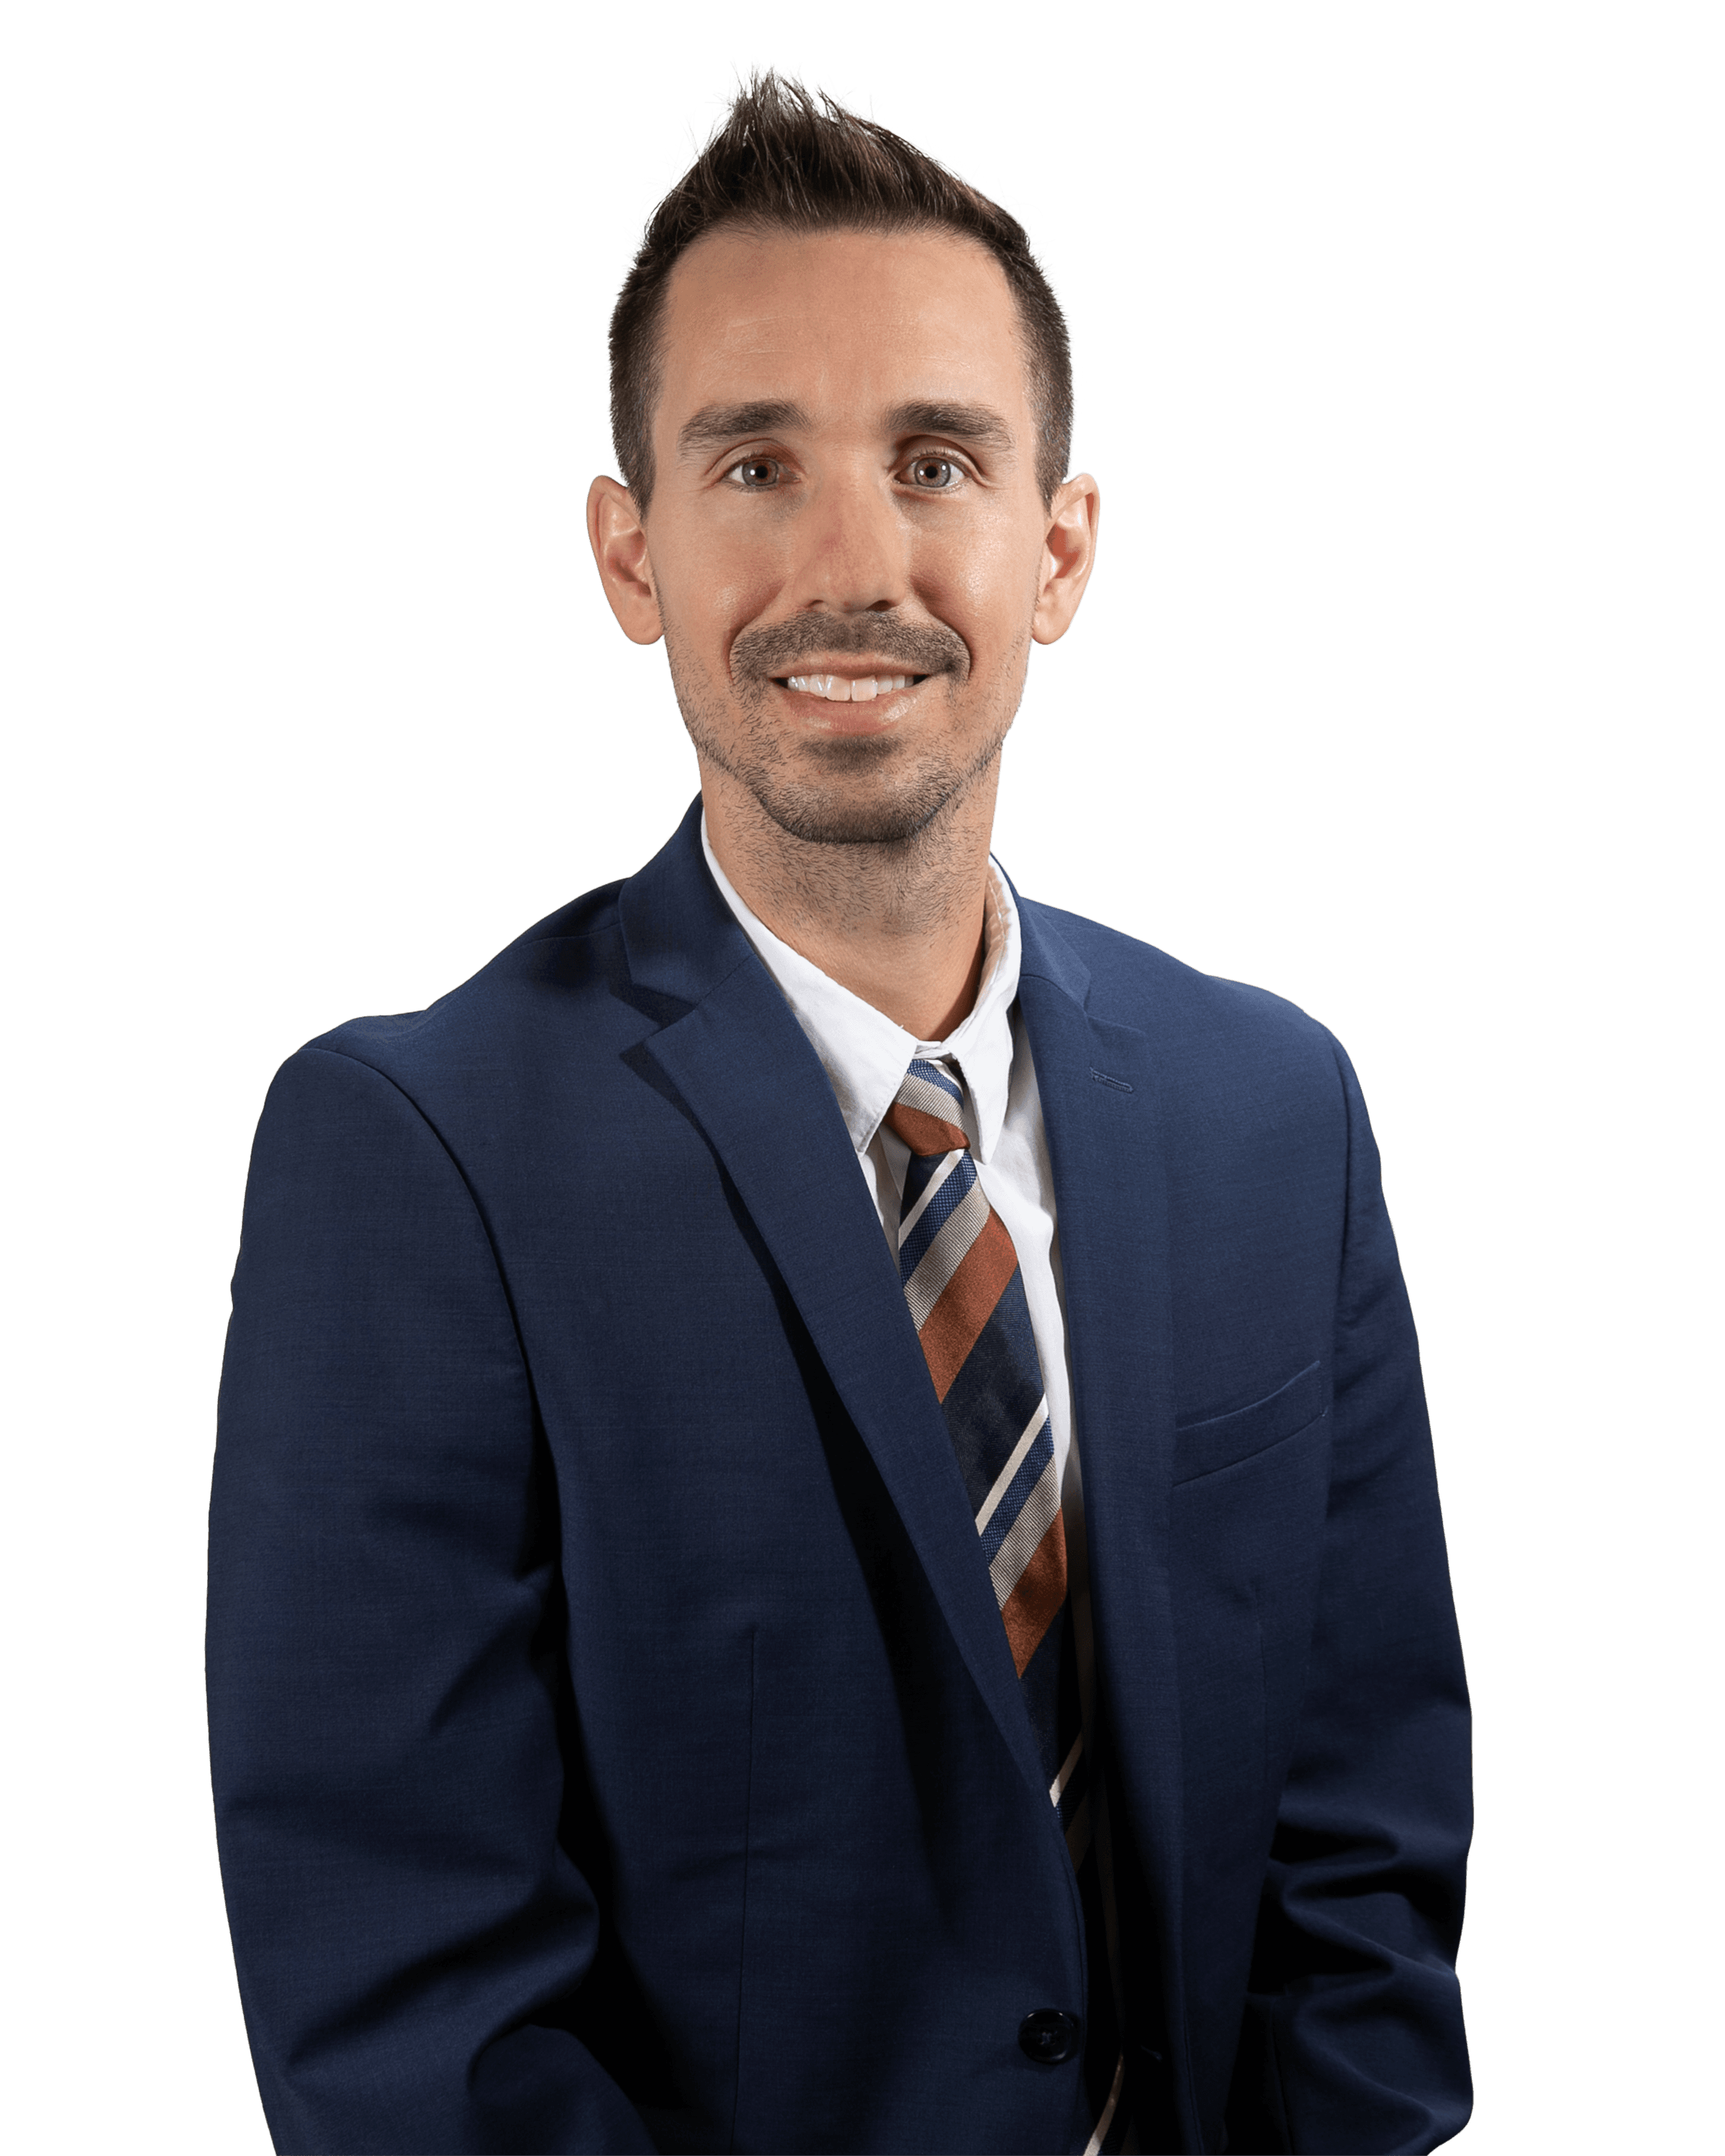
Lenny Whiting
Admitted 2012 · NV Bar #14822
I founded CPA Attorney LLC to fill the gap between accounting and legal strategy. With dual credentials as a licensed CPA and Nevada attorney, I help clients keep more of what they earn — legally and permanently.
Full bioAnswers to the questions we hear most often about advanced tax strategies.
Basic tax planning claims the deductions the tax code already offers. Advanced tax strategy restructures entities, depreciation, and retirement design so less income becomes taxable in the first place.
Entity restructuring, retirement plan design, and real estate cost recovery — strategies that change the timing or character of income rather than adding one more deduction.
The tax code has no official definition. The SEC's accredited-investor standard ($1 million net worth, excluding a primary residence) is the closest formal benchmark, though income complexity matters more for planning purposes than the net worth figure itself.
A study that reclassifies parts of a property into shorter depreciation schedules (5, 7, or 15 years instead of 27.5 or 39). Applied correctly, it can be part of a plan that cuts a qualifying owner's tax bill by roughly 15–35% a year.
It depends on how many qualifying components the property has, not its price alone. Properties dense with fixtures and site improvements — car washes, storage facilities, mobile home parks — tend to clear the break-even point; a bare single-tenant property may not.
Have questions or need legal assistance? Contact us today — our team is here to help. Whether by phone, email, or through our online form, we're ready to listen and provide the support you need.
Schedule a meeting at your convenience via Calendly.
Book a time